

A2A payments
Direct from the source
For years, bank accounts were where people kept their money and cards how they spent it. Across many markets, that distinction is starting to disappear. More and more, consumers are paying directly from their accounts, through real-time payment rails, bank transfers and using QR codes that sit at the heart of everyday online shopping. The appeal is pretty simple: money can move almost instantly and at a low cost, without needing a card in between.
Where A2A share is moving fastest
In some emerging markets, account-to-account payments are already ahead of cards and in others, it’s growing from a smaller base, but the direction is clear: the bank account itself is becoming a payment method.
South Africa’s A2A volume is forecasted to grow fastest by percentage, while Brazil adds the most in dollar terms.
Source: PCMI
Real-time becomes routine
Most major real-time payment rails across emerging markets were built with central bank or regulator backing. And when the infrastructure has that kind of support behind it, adoption can spread faster and more broadly than when a single private player has to build the market on its own.
Instant, everyday payments
Real-time payment systems such as SPEI in Mexico, PayShap in South Africa, Pix in Brazil, UPI in India or Raast in Pakistan move money between accounts in seconds, and they’re becoming a first choice for daily purchases, bills, and recurring payments, not just one-off transfers.
Thailand’s PromptPay already carries close to two in five online purchases. Colombia and South Africa are moving fastest among the larger A2A markets, while Türkiye and Chile, starting from a smaller base, are growing at the steepest relative pace.
In South Africa, CapitecPay carries over half of local bank-transfer volume and stands out as the region’s only tokenizable APM, showing how RTP infrastructure can support subscriptions just as well as one-off purchases.
- 2011NIBSS Instant Payment
Nigeria110M+ linked bank accounts
- 2016UPI
India550M+ users
- 2017PromptPay
Thailand81M+ registered users
- 2018DuitNow
Malaysia8.4B+ transactions in 2025
- 2019QRIS / BI-FAST
Indonesia66M+ QRIS users
- 2020Pix
Brazil177M+ users
- 2021Raast
Pakistan48M+ users
- VietQR
Vietnam40M users
- FAST
TürkiyeUS$ 3.2B processed/day by Dec 2025
- Transferencias 3.0
Argentina102M+ QR transactions in May 2026
- 2023PayShap
South Africa6M ShapIDs registered
- 2025Bre-B
Colombia34M+ registered users after 6 months
Figures are estimates as of Q4 2026, compiled from various sources, including central bank and national payment operator statistics (NPCI, Napas, Banco Central do Brasil, Bank Indonesia, NIBSS, PayNet, CBRT, Banco de la República, BCRA, Bank of Thailand, TCMB, SBP, BankservAfrica).

Real-time payments on repeat
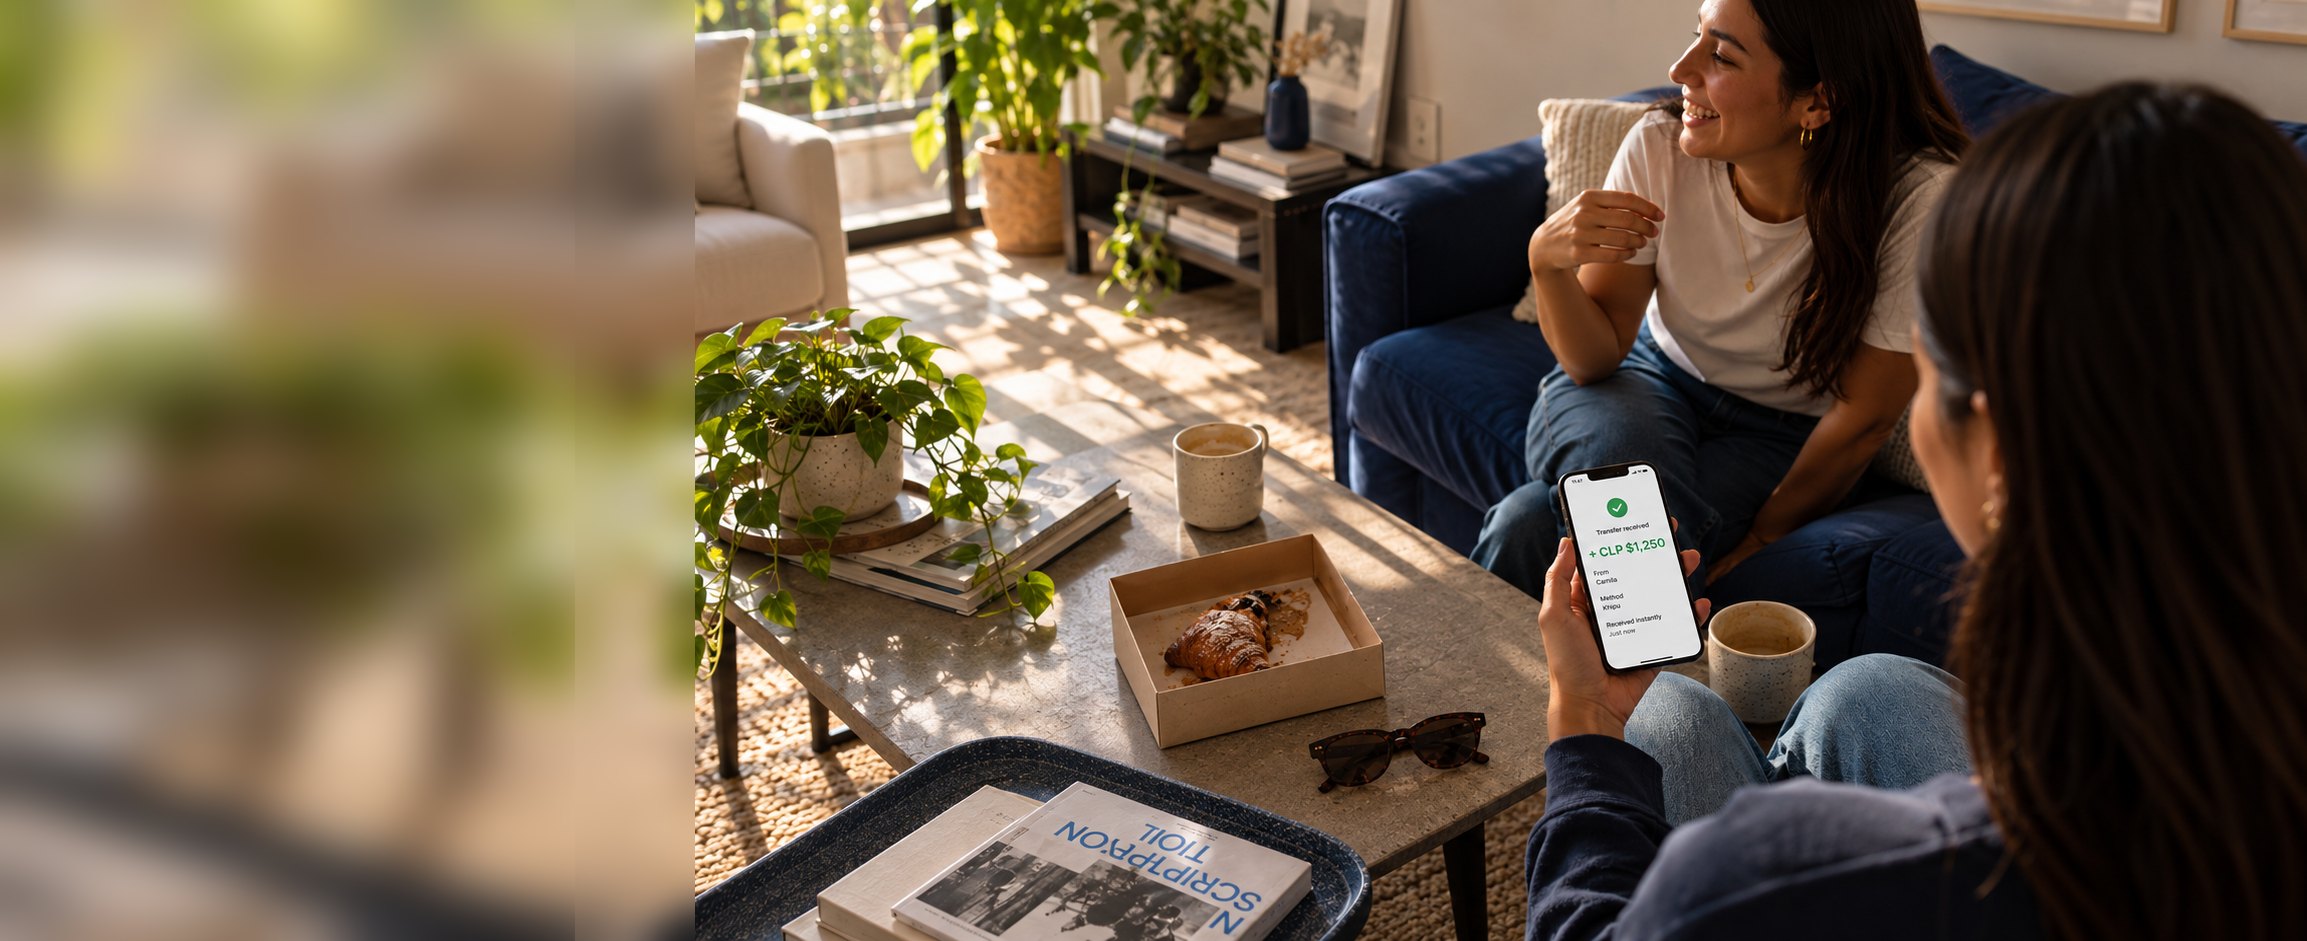
For one of our global merchants, Pix Automático, Brazil’s RTP solution for recurring payments, saw its share of TPV climb from 7% to 28% within five months. That kind of growth shows how quickly Brazilians are taking to new ways of paying with Pix.
One of the clearest signs that a payment rail has taken off is when people start using it without thinking about the payment itself. In Brazil, ‘faz um Pix’ is just part of everyday conversation. When a payment works its way into how people speak, you know it has become part of how they live, and it’s hard to imagine it going away.
Pay straight from your bank
Direct bank transfers remain particularly important where consumers are comfortable with banking apps but card penetration is lower. Colombia leads with over a third of online purchases paid by bank transfer, followed by Indonesia, South Africa, and Nigeria.
In Colombia, PSE carries the vast majority of online bank-transfer payments, while the newer Bre-B (real-time payment rail) is showing early traction. In its first months, Bre-B represented 9% of all APM transactions in the country, with around a quarter of that volume coming from entirely new users. Together, PSE and Bre-B are projected to push A2A payments past US$ 32B by 2028.
In Nigeria, bank transfer is proving it can grow the pie rather than just take a slice of it, as they expand the payment opportunity, not simply shift volume between methods.
One of our merchants in Nigeria saw bank transfers’ share climb from 20% to 35% of TPV in four months, consistently the channel bringing in new users other methods weren’t reaching.
What stands out across these markets is how differently bank transfers resolve locally. In some, one rail wins nearly everything (Türkiye’s FAST carries 85% of local bank transfers). In others, the mix stays contested: Chile alone runs five competing rails side by side, and South Africa’s CapitecPay, though the largest single player, still shares the field with other real alternatives.
Scan and pay
QR codes are acting as the front door to A2A payments in many emerging markets. A customer opens a banking app or wallet, scans a code, and pays directly from their account. That can make digital acceptance possible across everything from a street stall to an online checkout or a ride-hailing app, without relying on a card terminal.
Bolivia shows what happens when QR codes become part of the local payment behavior
One of our merchants saw QR codes climb to more than 80% of TPV within its first year of launch, alongside a 5.4x increase in total TPV.
That mirrors the broader market: 85% of payments made through mobile banking or eWallets in Bolivia now use QR codes.1 Recurring QR payments are also being developed, opening the door for the same payment behavior to move into subscriptions and other repeat purchases.
In Indonesia, QRIS plays a similar role, giving merchants from major retailers to street vendors a single QR standard to accept digital payments. In Pakistan, Raast is bringing the same idea to A2A payments, with QR helping move everyday transactions from cash to digital while bringing more people into the formal digital payments ecosystem.