Contáctanos

Conversion Engine

The local conversion engine behind your payment performance.

Talk payment performance

There’s a lot behind a payment

  1. Routing

    The route a payment takes.

  2. Network & Issuer

    How the network and the issuer respond.

  3. Authentication

    Whether fraud checks and authentication help or get in the way.

  4. Recovery

    What happens after a decline.

  5. Credentials

    Whether the credentials still work when the customer comes back.

Each one decides whether a sale becomes revenue.

And in the markets of the future, the right answer changes from one market to the next.

Performance is decided locally

Card payments convert up to

20pp*

more when
processed locally instead of from abroad

* Based on dLocal tests and merchant use cases in specific emerging markets, comparing local processing with international-only acquiring. Results vary by merchant, market and payment flow.

Running at full speed, market by market.

More approved revenue across emerging markets, with risk under control.

Optimization Suite

The technology we put to work across the payment journey.

Smart Routing

up to +4pp1 higher conversion

Smart Requests

up to +2pp1 higher conversion

Our local edge

Our teams on the ground, raising approvals market by market.

  • South Africa · BNPL +15pp higher conversion
  • Colombia · PSE +5.3pp higher conversion

Your growth passport

The reach to perform and grow across 60+ emerging markets.

  • 60+Markets
  • 1000+Payment methods
  • One APIOne contract
Optimization Suite

Every payment is a series of decisions

Our Optimization Suite puts technology to work at each of those moments, learning from local data in every market we process, so more of your payments become approved revenue.

  1. 01Approve
  2. 02Recover
  3. 03Retain

Managing risk across the whole journey Up to +4pp conversion with Smart 3DS and -0.25pp chargebacks with dLocal Defense.

01. Approve

More payments approved on the first attempt.

  • Smart Routing

    Finds the best path for every payment.

    Up to4pp1higher conversion

  • Smart Requests

    Shapes each one for the issuer receiving it.

    Up to2pp1higher conversion
See how we approve more
02. Recover

A decline doesn’t have to be the end of the payment.

Retry Intelligence knows when to try again and where, with a fallback to the next-best acquirer, recovering sales within card network rules.

  • Retry Intelligence

    Up to1pp1higher fallback conversion

See how we recover more
03. Retain

Make the next payment easier to come back to.

Network Tokenization and Card Account Updater keep saved credentials working as their details change.

  • Network Tokenization

    Up to3pp1higher conversion

  • Card Account Updater

    Up to2pp1higher conversion

See how we retain more

1 Based on dLocal tests, data analyses and results observed with live merchants. Results vary by strategy, payment method, industry and market, and are not a promise of uplift.

Local Edge

Conversion problems don’t all look the same

Sometimes the answer is in the route, retry or authentication decision. Sometimes it means looking beyond the transaction.

What we did

Our team spotted that the bank’s anti-fraud rule was flagging legitimate PSE payments. The bank adjusted it, raising conversion on PSE payments from that bank across our merchants.

Colombia · PSE +5.3pp higher conversion

Internal dLocal data, 2026. Results compare performance before and after our work, or enrolled and non-enrolled payments, for one merchant or across all merchants on each payment method. Results vary by merchant, market and payment flow.

Our teams use what we’re seeing in the data to understand what changed locally then work directly with issuers, acquirers, payment providers, and regulators on the problem itself.

Growth Passport

Now multiply that by 60+ markets

What works in one emerging market won’t necessarily work in another.

Each market has its own issuers, acquirers, payment methods, regulations and infrastructure.

and these are the reasons a payment might succeed or fail.

That complexity is also where demand is growing.

USD$3.7T1

Digital payments in emerging markets by 2028.

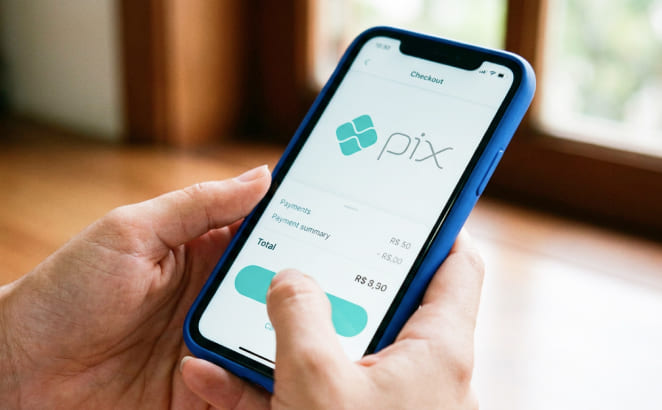
Pix at checkout

+55%

Adding Pix brought new customers and more transactions within five months.3

56% of India’s eCommerce payments run on UPI. In Brazil, Pix accounts for 44%.2

  • India · UPI 56%
  • Brazil · Pix 44%
Asia

20%

Yearly growth of digital payments in Asia, the region leading that growth.1

  1. Americas Market Intelligence (AMI) for dLocal, estimate for 39 countries where dLocal operates, excluding China, 2022 to 2028.
  2. PCMI, 2025 eCommerce payment method shares.
  3. dLocal, The Local Code, 2026.

Capture that growth in every market, with a partner that knows how each one works

See the markets where we operate and the local payment methods your customers already use in each one.

One APIand one Contract

1,000+

Local payment methods

Explore how people pay

Made to convert where payments are hardest.

Find out where your payment performance could go further across emerging markets.

Talk payment performance

Escanea el siguiente código QR con tu celular para contactarnos a través de WeChat.

Un lugar es mucho más que lo que ves en el mapa

Acércate a cómo viven, compran y pagan las personas.

Descifra The Local Code

Actualizaciones del aviso de privacidad - Colombia

Le informamos que una versión actualizada del aviso de privacidad entrará en vigor el primero de julio de 2025. Hemos realizado cambios en las siguientes secciones:
4. Cuándo podemos revelar los datos personales;
8. Cookies;
9. Sus derechos;
10. Procedimientos para que los titulares puedan ejercer sus derechos en Colombia;
13. Cambios.

Lea el nuevo aviso de privacidad