BNPL at checkout: should merchants offer it?
Buy Now, Pay Later can make a checkout more flexible, but adding installments is a business decision. Here’s how merchants can assess whether it fits their customers, economics and operations.
Start with the customer and the purchase
Buy Now, Pay Later (BNPL) lets an eligible customer pay for a purchase in installments over an agreed period. Terms —interest, fees, eligibility and repayment schedules— vary by provider and market.
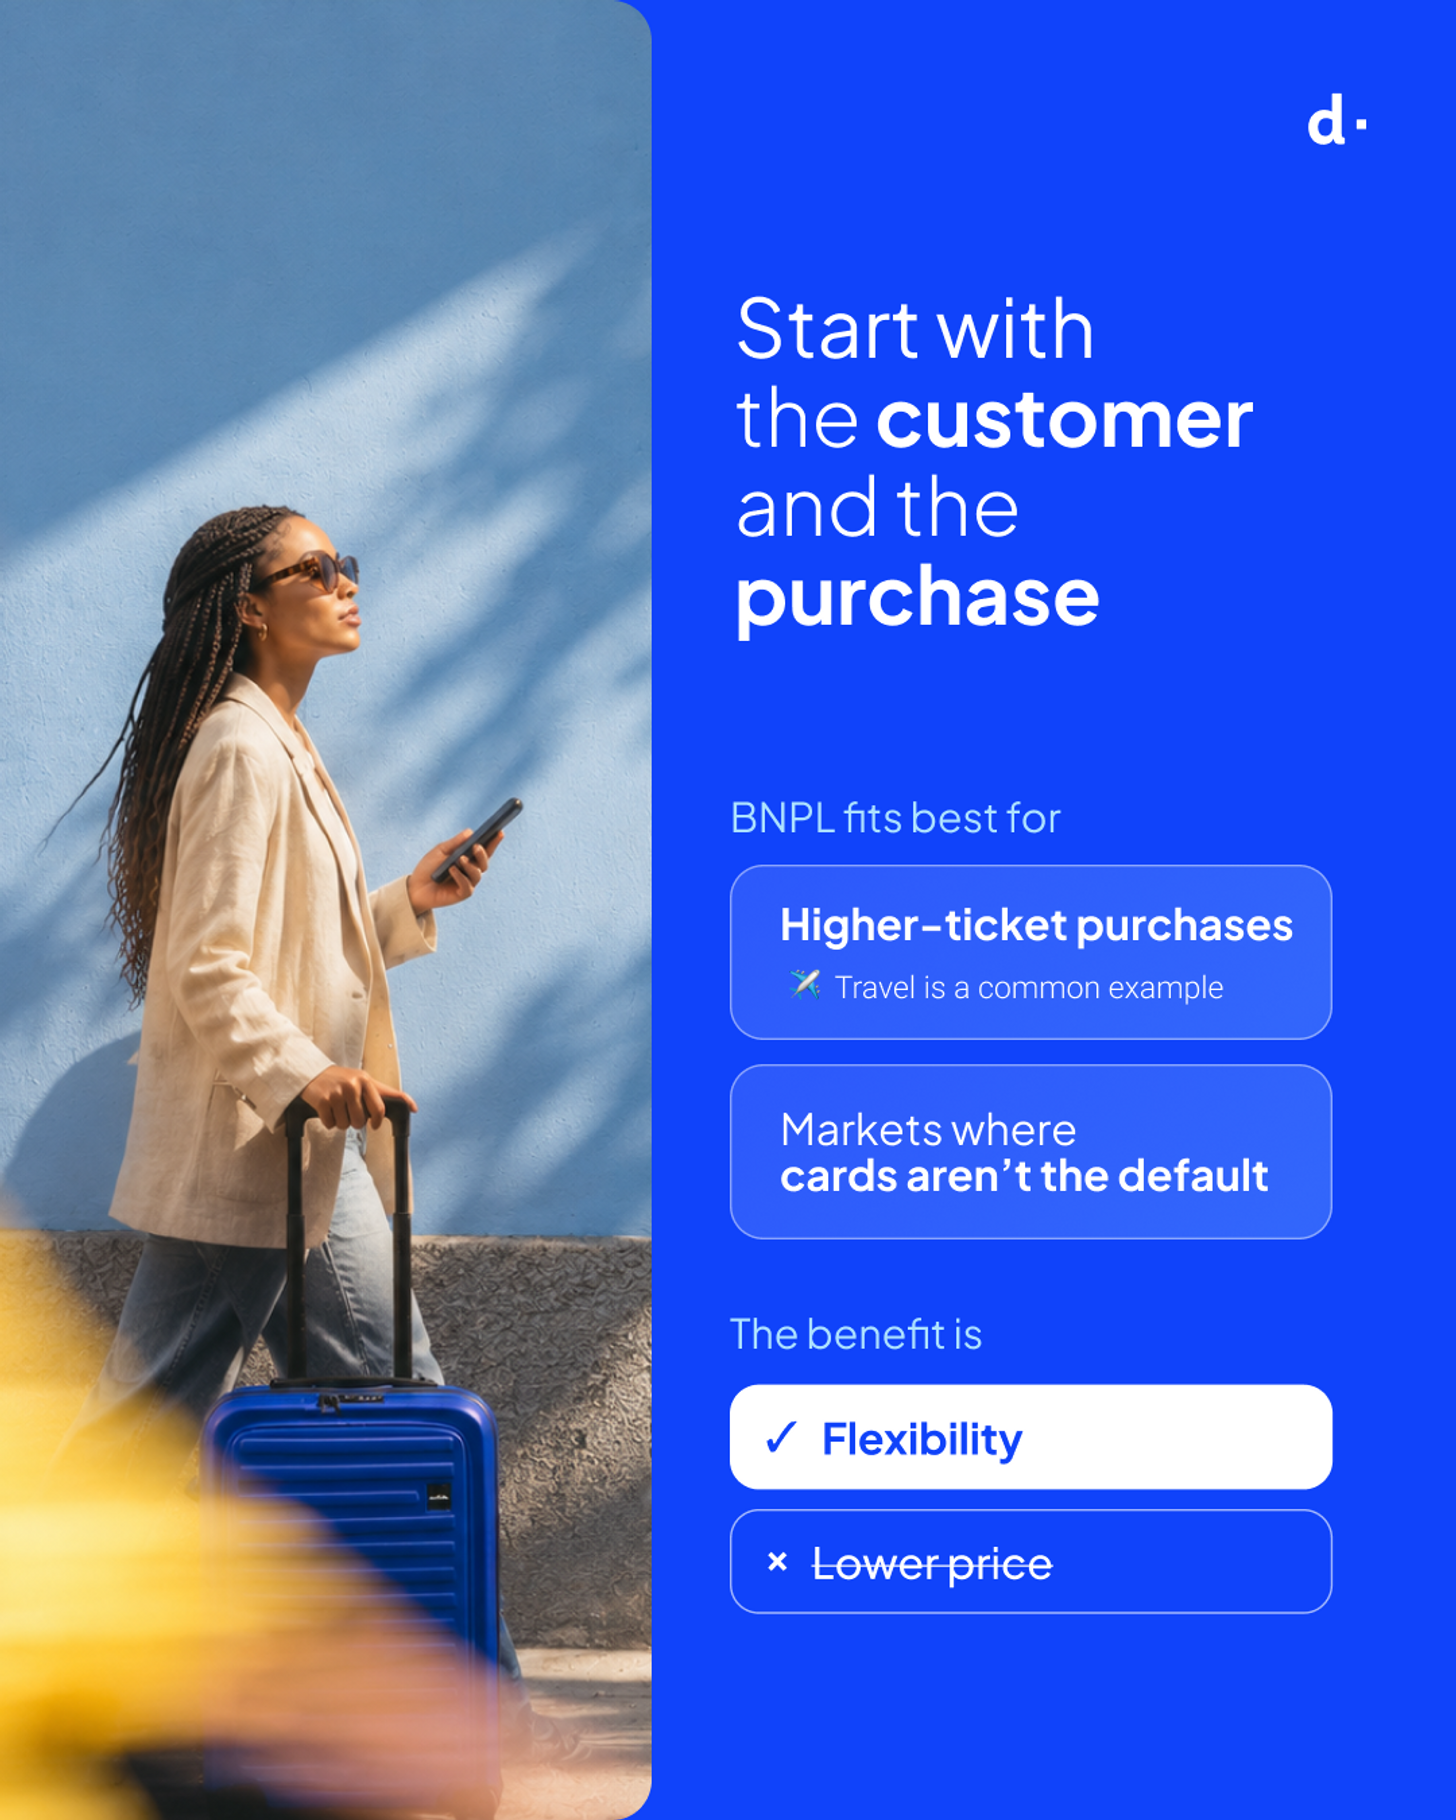
Fit may be stronger for higher-value purchases or markets where cards are not the default. Travel is one example: installments can make a flight or package feel more manageable. But fit depends on local habits, category and customer base. BNPL should complement relevant local methods, not replace broader choice.
What BNPL can offer customers
For eligible customers, installments can spread a purchase across scheduled payments instead of requiring the full amount upfront. This may make higher-value purchases easier to plan for and offer another way to pay where credit cards are less accessible or not a customer’s preferred option.
The benefit is payment flexibility, not necessarily a lower total price. Costs and terms depend on the provider and market. Merchants can help customers make an informed choice by clearly showing the total amount payable, installment amounts, due dates, fees and eligibility requirements before checkout.
Weigh the upside against the full cost
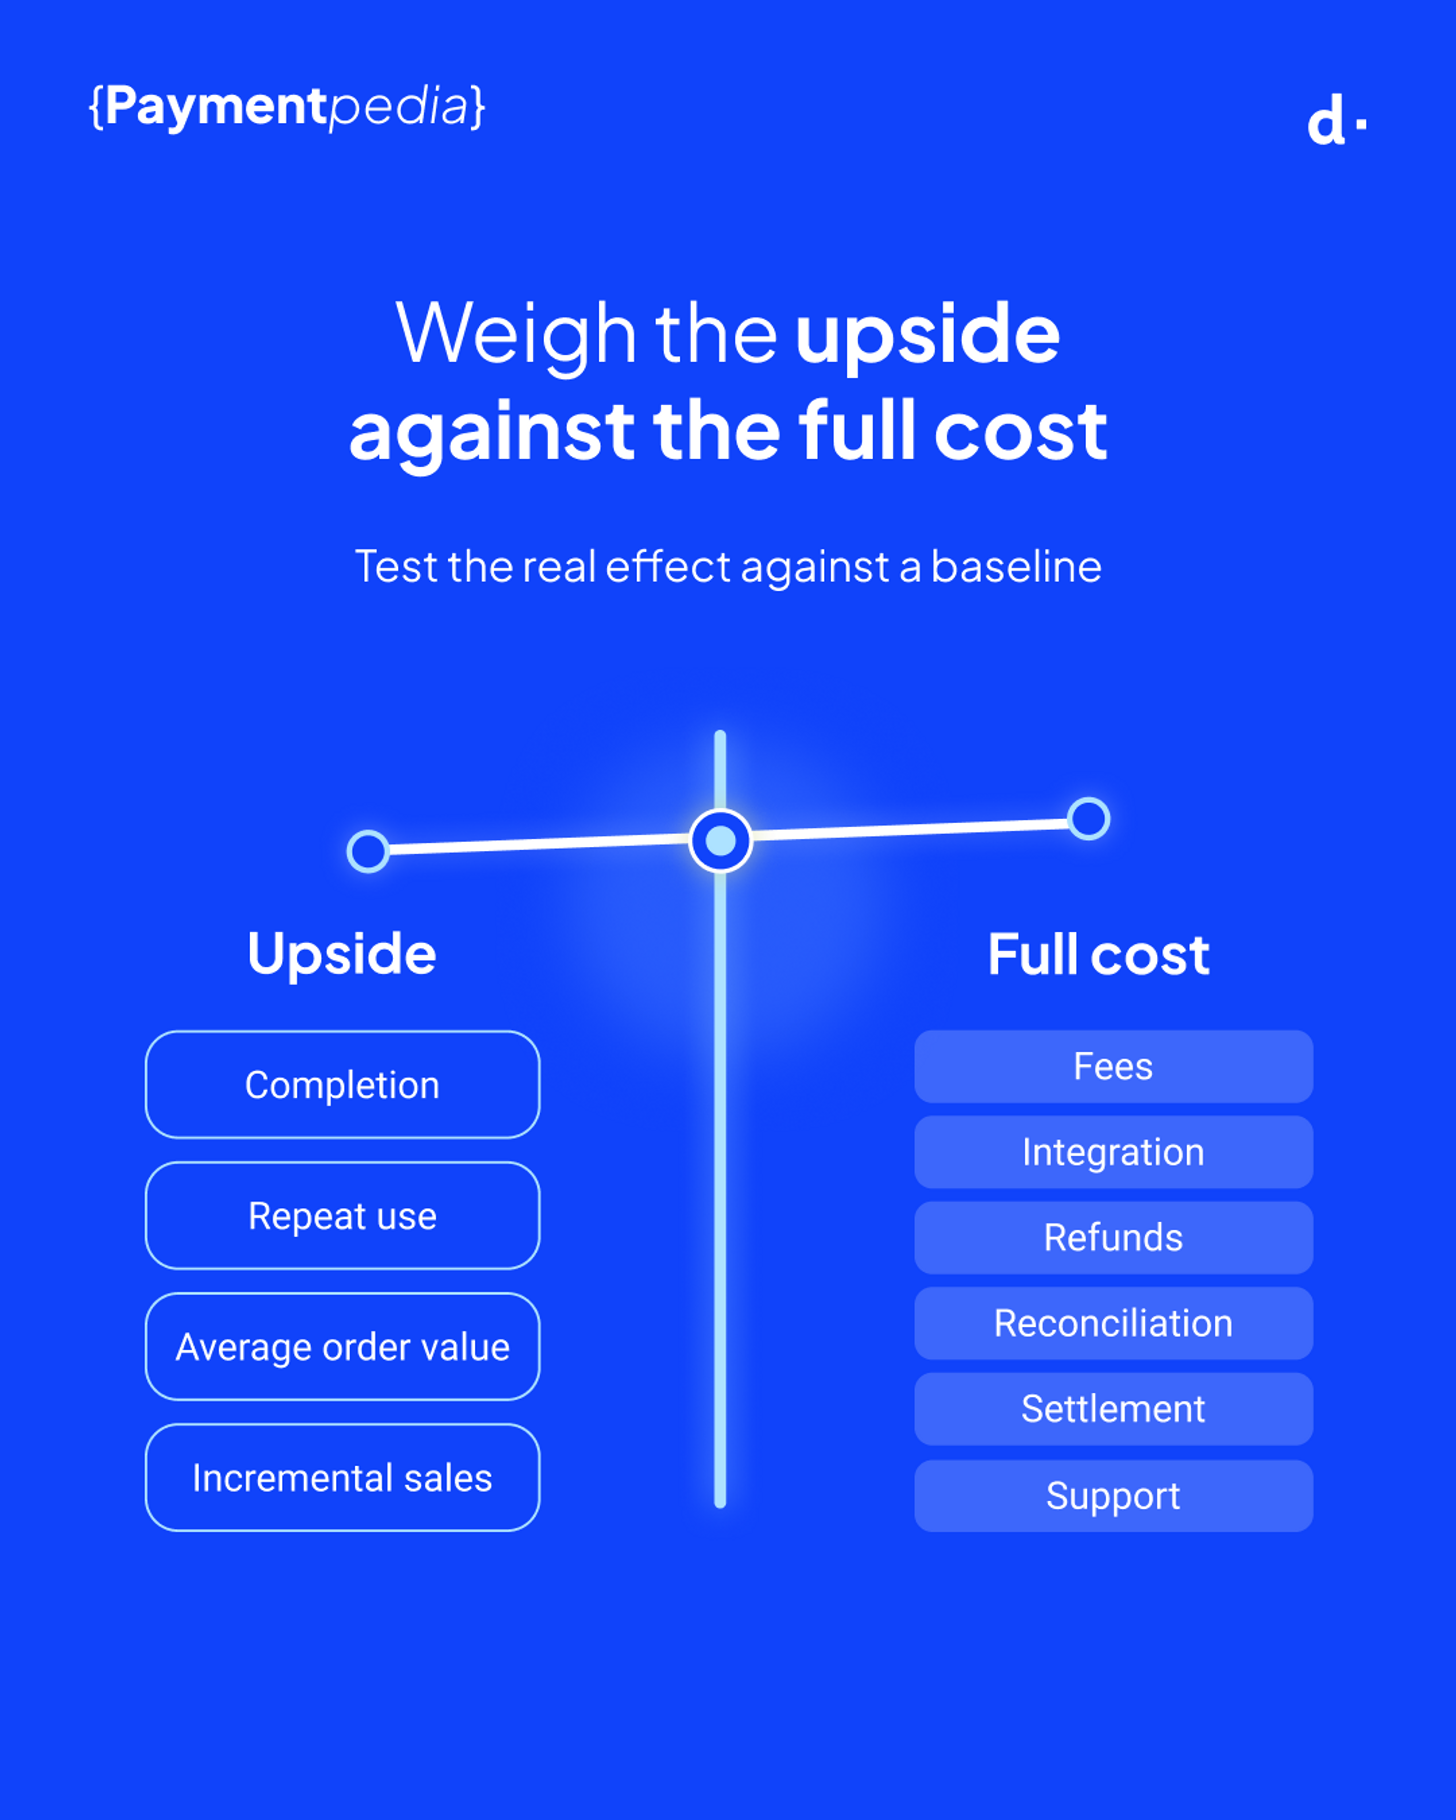
Installments may help customers complete a purchase or support larger baskets, but the effect should be tested. Compare completion, average order value, repeat use and incremental sales with a baseline; check whether customers are switching from another payment method. Results vary by market, provider, device and checkout design.
The commercial calculation should include more than the provider’s fee. Consider the cost of integration, refunds, reconciliation, customer support and any operational work across markets. Clarify when funds are settled, who handles collection and what happens when an order is cancelled or returned. In some models, the provider assumes the customer credit risk and the merchant is paid upfront; responsibilities and settlement terms depend on the specific arrangement. A clear contract and operating process matter as much as the payment button.
BNPL Fuse can simplify access to multiple local BNPL providers, so merchants may not need to manage a separate integration and operating process for each one.
Make the choice clear—and measure the experience
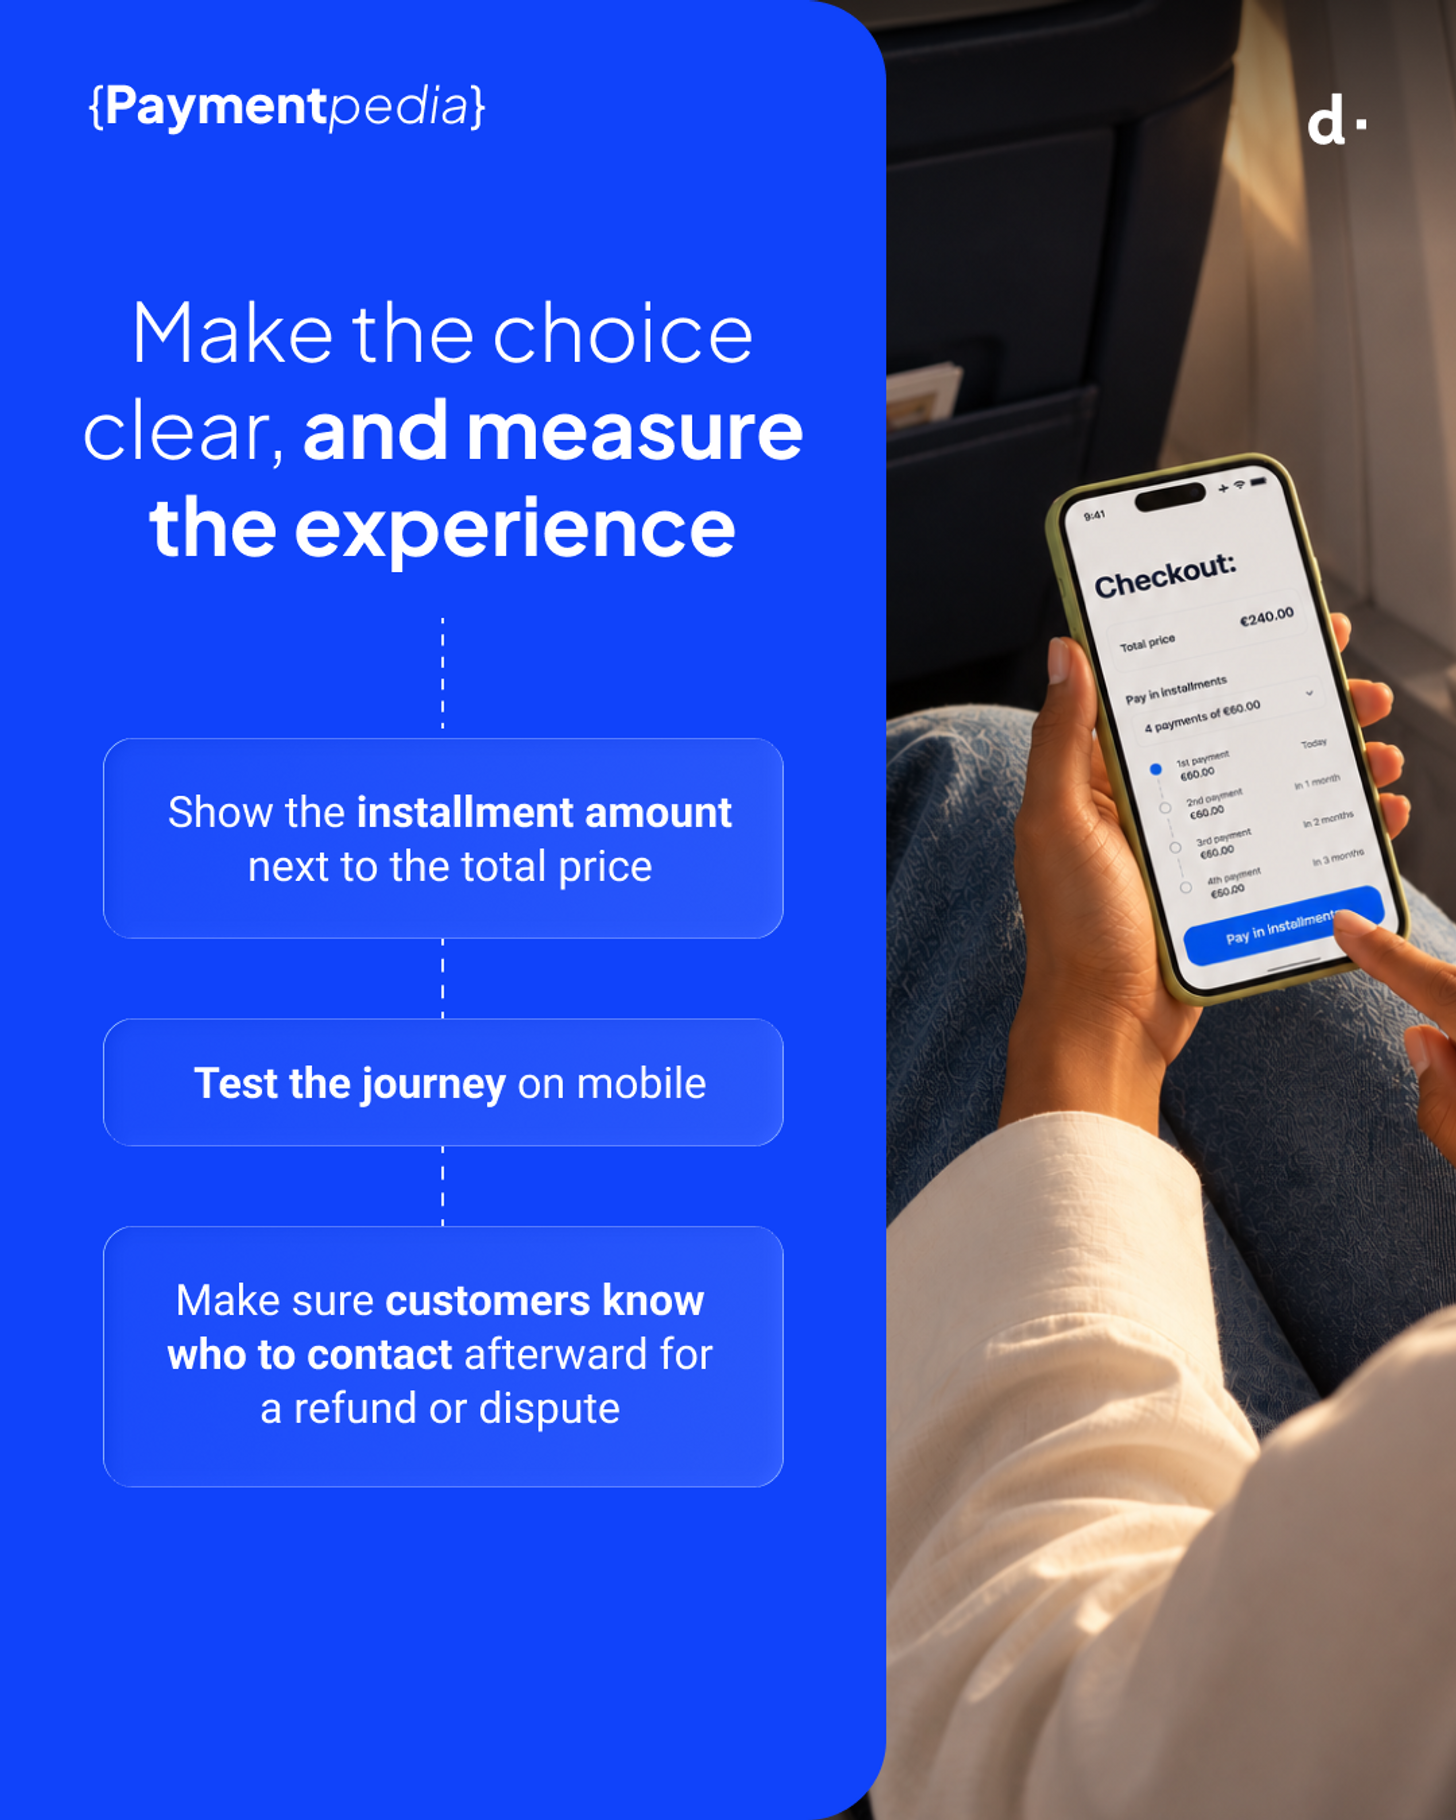
A confusing BNPL option can add friction rather than remove it. Show the installment amount alongside the total price, explain relevant fees and due dates, and make the provider and eligibility step clear before a customer commits. Test the journey on mobile as well as desktop: redirects, extra logins or unclear approval outcomes can interrupt checkout.
Merchants should also plan for the post-purchase experience. Customers need to know whom to contact about a repayment, refund or dispute. Teams need a consistent way to track transaction status and reconcile payments. Where several providers or countries are involved, local rules, disclosure requirements and consumer protections should be checked for each market. Offering financing responsibly means presenting it as an option—not implying that borrowing is suitable for everyone.
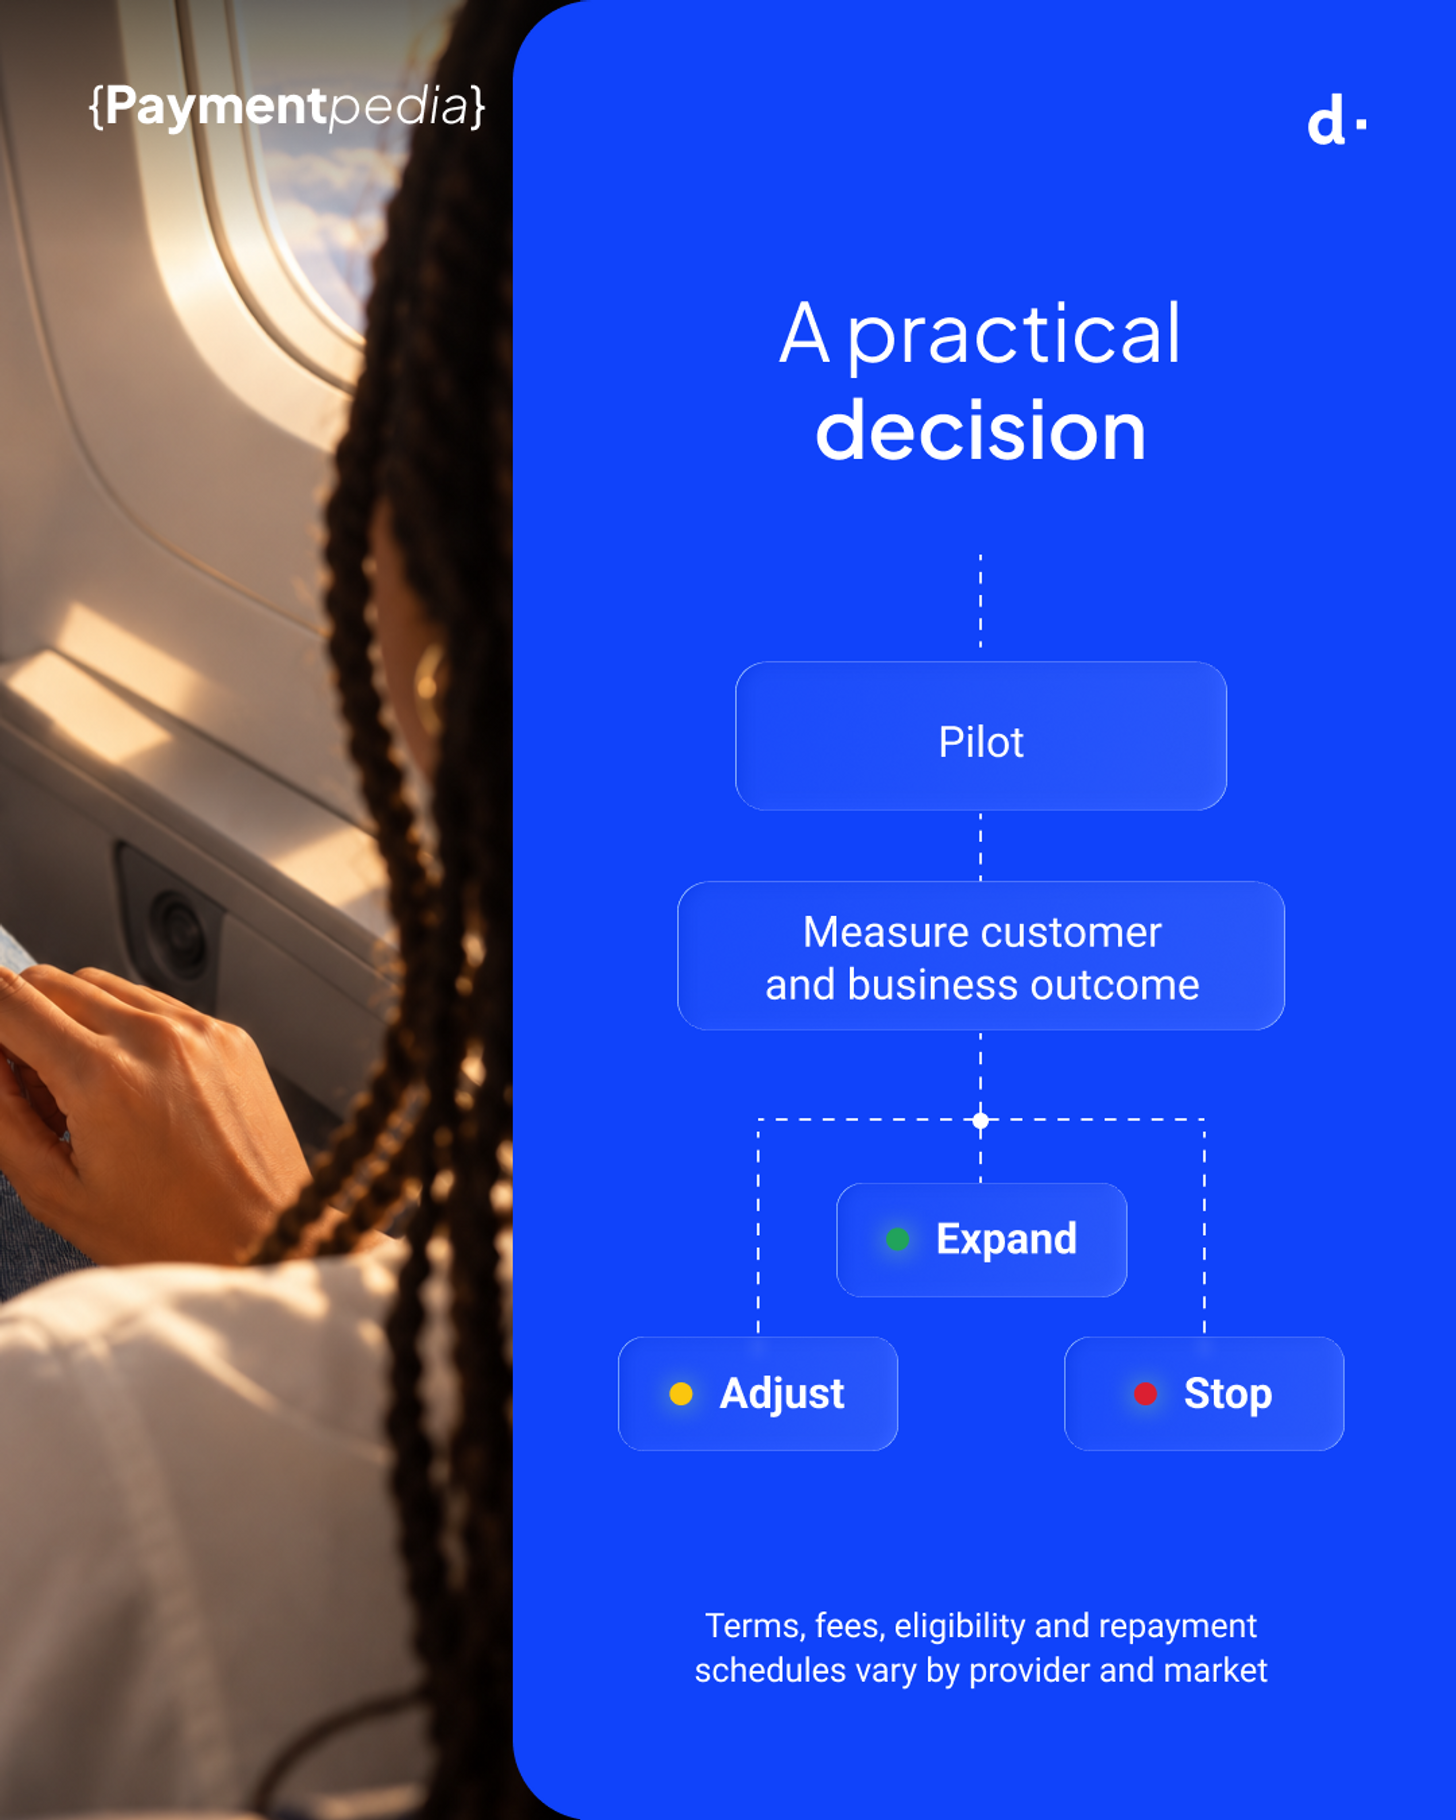
A practical decision
Before adding BNPL, define the customer problem it is meant to solve, estimate the total cost, verify local and operational responsibilities, and run a measured test against a clear baseline. Keep the option transparent, monitor customer outcomes as well as sales metrics, and be prepared to adjust or remove it if it creates more confusion than value. The best checkout is not the one with the most buttons; it is the one that gives customers a relevant, understandable choice.